A rejected FSA or HSA claim is almost never about the expense. It’s about the paperwork. Here are the 12 documentation mistakes that trigger denials, and the fixes.
You paid for a legitimate medical expense, uploaded the receipt, and days later the claim bounces back as denied or flagged for “additional documentation.” The frustrating part is that the expense was probably fine. What failed was the proof. These plans run on a strict documentation standard, and a receipt that would satisfy any store falls short of what the IRS wants to see.
Learn what a valid receipt actually contains and the twelve ways people fall short, and most of these denials stop happening.
In Brief
An FSA or HSA claim gets rejected when the documentation is incomplete, the item is not eligible, or the timing is off. Every receipt needs five things: the provider or merchant name, the date of service, a description of what was bought, the amount, and the patient. A credit-card receipt has none of that detail, which is why it is the single most common cause of a denial. Fix the paperwork, and the claim usually clears.
The five things every receipt needs
Start here, because it fixes most denials on its own. A valid itemized receipt or Explanation of Benefits has to show the provider or merchant name, the date of service, a description of the service or item, the amount paid, and the patient’s name. A credit-card receipt, a canceled check, or a treatment estimate does not meet the standard, because none of them proves what you actually bought. If your reimbursement keeps getting rejected, this is almost always the reason.
FSA and HSA are not the same here
The word “rejected” means different things depending on the account. A health FSA, dependent care FSA, or HRA requires you to substantiate expenses to your employer or plan administrator, so a claim can be formally denied for bad documentation. An HSA is your own account, and the IRS does not make you substantiate a withdrawal to anyone at the time you take it. But that freedom has a catch: you are responsible for keeping proof for seven years in case of an audit. So if an “HSA reimbursement” was rejected, you are usually dealing with a claims portal or an FSA, and the receipt rules below apply.
Documentation mistakes
The biggest category, and the easiest to fix. These are about the proof itself.
- Submitting a credit-card receipt. It shows an amount and a store, not what you bought or the date of service, so it fails on its own.
- Missing one required field. A receipt without the patient name, the description, or the date of service gets kicked back even if everything else is there.
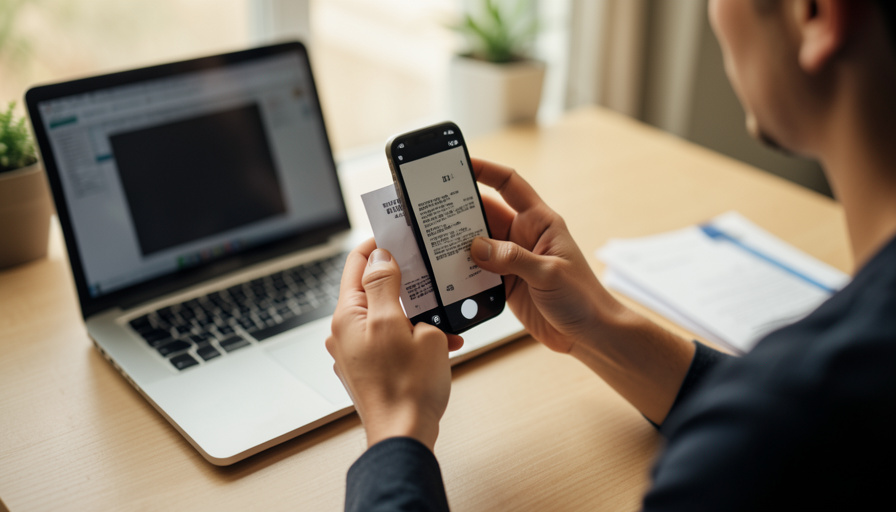
- An illegible or cut-off image. A blurry photo or a receipt with the total cropped out cannot be verified, so photograph the whole thing in good light.
- Sending an estimate or a balance-forward statement. “Amount you may owe” or a running balance is not proof of a paid, eligible expense. You need the itemized detail.
Eligibility mistakes
Here the paperwork is fine, but the expense does not qualify, or does not qualify yet.
- The item is not eligible. Check the plan’s list and IRS Publication 502 before you submit, since everyday toiletries and most general-health items are not covered.
- A dual-purpose item with no Letter of Medical Necessity. Things like supplements, some braces, or wellness equipment need a provider’s letter stating they treat a specific condition. Without it, they read as personal expenses.
- An expense for someone not on the plan. Reimbursement covers you and your qualifying dependents. A claim for a person outside that circle gets denied.
- It was already paid by insurance. You can only be reimbursed for your own out-of-pocket cost, so a claim for an amount insurance covered will bounce.
Timing and process mistakes
These trip up even careful savers, because they are about the calendar and the card, not the receipt.
- The date of service is outside your plan period. FSAs cover expenses incurred during the plan year, plus any grace period or carryover your plan allows. A service dated too early or too late is not eligible.
- Submitting the same expense twice. A duplicate of a claim you already filed, or one that overlaps your card payment, gets rejected as a repeat.
- Ignoring a card substantiation request. When an FSA debit card charge cannot auto-verify, the administrator asks for a receipt. Miss that request and your card can be frozen, and your employer may recover the amount through payroll.
- Using the wrong account. A limited-purpose FSA covers only dental and vision, and a dependent care FSA is separate from health care. Submitting to the wrong one gets it denied.
This article is general information, not tax, medical, or financial advice. Plan rules, eligible-expense lists, and deadlines vary by plan and change over time, so confirm details with your plan administrator or a qualified professional before you act.
What to do when a claim is rejected
Move fast and fix the specific gap. Request a fully itemized receipt or an Explanation of Benefits from the provider that shows all five required fields, and resubmit. If the flag was a card substantiation request, respond before the deadline so your card is not deactivated. For a dual-purpose item, get a Letter of Medical Necessity from your provider and attach it. And if you believe the denial is wrong, use your plan’s appeal process, since administrators do reverse denials when the documentation finally matches.
Frequently Asked Questions
Why does my FSA keep rejecting my receipts?
Almost always because the receipt is not itemized. It needs the provider, date of service, description, amount, and patient name. A store or credit-card receipt lacks the description and date of service, so it fails.
Do I need receipts for HSA purchases?
Not to withdraw the money, since an HSA is your own account. But you must keep documentation for about seven years in case the IRS audits your return, so save every itemized receipt.
What is a Letter of Medical Necessity?
It is a note from your provider stating that a dual-purpose item, like a supplement or wellness device, is treating a specific medical condition. It turns an otherwise personal expense into an eligible one.
Can I still buy over-the-counter medicine with my FSA?
Yes. Since the CARES Act, over-the-counter drugs no longer need a prescription to be eligible, and menstrual care products were added to the list. Keep the itemized receipt anyway.
My FSA card got frozen. What happened?
A charge could not be auto-verified and you did not submit the requested receipt in time. Provide the itemized documentation for that charge, and the administrator can reactivate the card once it is substantiated.
Can I appeal a denied FSA claim?
Yes. Fix the documentation gap first, then submit through your plan’s appeal process. Many denials are reversed once the receipt shows all the required details.
Final Takeaway
Treat your FSA and HSA claims as a documentation task, not a spending one. Photograph the full itemized receipt every time, confirm it shows the provider, date, description, amount, and patient before you upload, and answer any substantiation request before your card locks. The expense was usually fine all along; the receipt was the problem. For related help, see our guide to spotting errors on your medical bills, and browse more in ShoutPost’s Health section.
Leave a Reply
You must be logged in to post a comment.