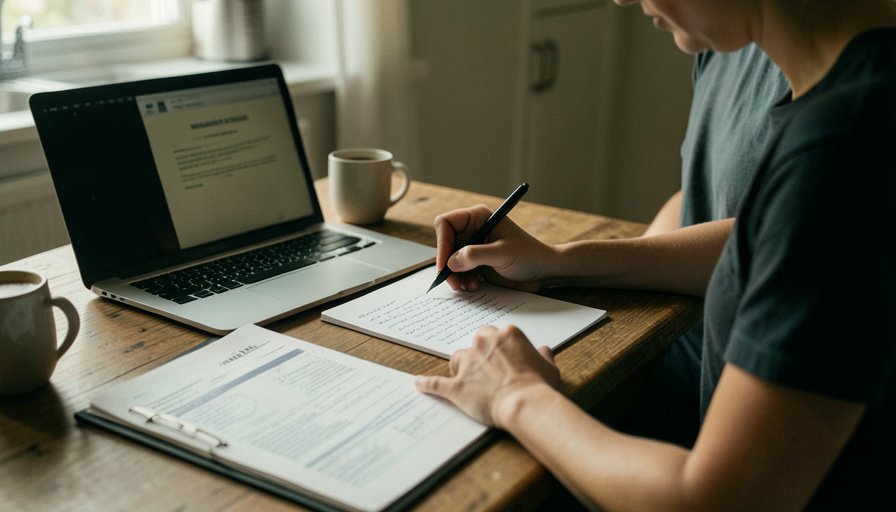
Insurers deny about one in five claims, yet almost no one appeals. A clean appeal letter wins more often than you’d think. These nine mistakes get it delayed.
Here is the number that should make you pick up a pen. In 2023, insurers on HealthCare.gov denied about 20% of all in-network and out-of-network claims combined, yet consumers appealed fewer than 1% of them. When people did appeal, insurers reversed themselves a large share of the time. The denial letter is not the final word. It is an invitation to a process most people never accept.
And most denials are not even about your health. The single largest bucket of reasons is administrative and “other,” which means paperwork, codes, and process, not a doctor deciding your care was unnecessary. That is good news, because a paperwork denial is exactly what a well-built appeal letter is designed to fix. It is also why a sloppy letter fails: it adds new paperwork problems on top of the old one.
The Short Version
An appeal letter gets delayed or kicked back when it is missing the identifiers a reviewer needs, misses the deadline, or fails to attach proof. Include your member ID, claim number, and date of service at the top, name the exact denial reason you are rebutting, attach a medical necessity letter and records, file within 180 days, send it to the right place, and keep dated proof you sent it. Short and complete beats long and emotional every time.
Why the letter matters more than you think
Appealing works often enough to be worth the afternoon it takes. In its review of 2023 marketplace data, KFF found that insurers denied roughly one in five in-network claims, that consumers appealed under 1% of them, and that even so, a meaningful share of appeals overturned the original decision. One member on r/InsuranceClaims described a $6,200 denial reversed in eleven days after a single tight one-page letter. The letter is the lever, and these nine mistakes are what jam it.
9 appeal letter mistakes that delay your claim
1. Leaving out the claim number, member ID, or date of service
Automated intake routes appeals by these identifiers. Miss one and your letter cannot be matched to the denial, so it sits or bounces back. Put all three in a header block at the very top, copied exactly from your Explanation of Benefits.
2. Not naming the exact denial reason
A reviewer needs to know which decision you are contesting. “I think this is unfair” gives them nothing to act on. Quote the specific reason and code from the denial notice, then rebut that reason directly.
3. Missing the 180-day deadline
For most plans, you have 180 days from the denial notice to file an internal appeal. Miss it and the insurer can reject the appeal on timing alone, without ever weighing your case. File early and state the denial date in your letter.
4. Sending no supporting documentation
A letter with no evidence is an opinion. Attach the records that prove your point, and for anything involving care decisions, include a letter of medical necessity from your provider. That doctor’s letter is often the piece that turns a denial around.
5. Mailing it to the wrong place
Appeals, claims, and general correspondence often go to different addresses, fax lines, or online portals. A letter sent to the wrong one is effectively lost time. Confirm the appeal-specific submission method on your denial notice or the insurer’s site.
6. Not stating which appeal you want
There is an internal appeal and, if that fails, an external review, plus expedited tracks for urgent situations. If your letter does not specify, it may be logged as the wrong type. Name it: standard or expedited, internal appeal or request for external review.
7. Writing a long, emotional letter
Reviewers skim. A five-page account of your frustration buries the facts they need, while a focused page gets read and acted on. Lead with the ask, give the facts, list the evidence, and stop. The one-page reversal above was not an accident.
8. Ignoring your own plan’s language
Your strongest argument is often the insurer’s own document. Find the section of your plan or Summary of Benefits that covers the service and quote it, so the reviewer sees the denial contradicts the policy you both signed.
9. Keeping no proof you sent it
If a deadline dispute arises, “I mailed it” is not evidence. Use the portal’s confirmation, a fax receipt, or certified mail, and keep a copy of everything. Dated proof of timely submission protects you if the claim stalls.
What a clean appeal letter contains
Structure does most of the work, so build the letter in this order and keep it to about a page.
- A header with your name, member ID, claim number, and date of service.
- One sentence stating what you want: the denial overturned and the claim paid.
- The exact denial reason quoted, followed by a direct, factual rebuttal.
- A short list of the attachments: records, the medical necessity letter, and the relevant plan language.
- The denial date and a line noting you are filing within the appeal window.
- Your signature, the date, and your contact information.
If the internal appeal fails
A “no” from the insurer is not the end. You can request an external review, where an independent third party arranged through your state or the federal government looks at the case fresh, and their decision binds the insurer. For urgent medical situations, you can ask for an expedited external review at the same time as your internal appeal rather than waiting. Note the external-review deadline the day your internal appeal is denied, because that clock starts immediately.
This article is general information, not medical, legal, or insurance advice. Appeal rights, deadlines, and procedures vary by plan and state, so follow the specific instructions on your denial notice, and consider a patient advocate or your state’s consumer assistance program for help with a complex case.
Frequently Asked Questions
How long do I have to appeal a denied claim?
For most plans, 180 days from the date of the denial notice for an internal appeal. Some plans allow less time, so check your notice and file as early as you can rather than waiting.
Does appealing a health insurance denial actually work?
Often enough to be worth it. A meaningful share of appeals overturn the original denial, and many denials are administrative errors that a clear letter with the right documents resolves.
Do I need a lawyer to write an appeal letter?
Usually no. Most appeals are won with a concise letter, the right identifiers, and a medical necessity letter from your doctor. For large or complex cases, a patient advocate or attorney can help.
What is a letter of medical necessity?
It is a statement from your provider explaining why the treatment was medically appropriate for your condition. It is one of the most persuasive attachments you can include, especially for care denied as unnecessary.
What if my situation is urgent?
Ask for an expedited appeal, and for urgent cases you can request an external review at the same time as the internal one. Say clearly in your letter that the situation is time-sensitive and why.
What happens at external review?
An independent reviewer outside the insurance company reexamines your claim, and their decision is binding. If they side with you, the insurer must cover the service.
The Bottom Line
The denial letter counts on you not writing back, and the data shows that bet usually pays off for the insurer. Do the opposite. Put your identifiers up top, name the reason, attach the proof, respect the deadline, and keep it to a page. A boring, complete letter beats a heartfelt, incomplete one, and it is the version that gets your claim reviewed instead of shelved. For related help, see our guides to spotting errors and fraud on your medical bills and more in ShoutPost’s Health section.
Leave a Reply
You must be logged in to post a comment.